SSDI vs SSI: 5 differences that change your rent math
People mix up SSDI vs SSI constantly, and it's not a small mix-up. They're run by the same agency, they both start with "S-S," and they answer completely different questions about your money.
Get them confused and you'll misjudge whether a pension, an annuity, or part-time work is going to shrink your check. That's exactly the question that trips people up in comment sections every day: "I have this other income, will it count against me?" The answer depends entirely on which program you're on.
What's in this article
two benefit letters side by side]
The core difference in one sentence
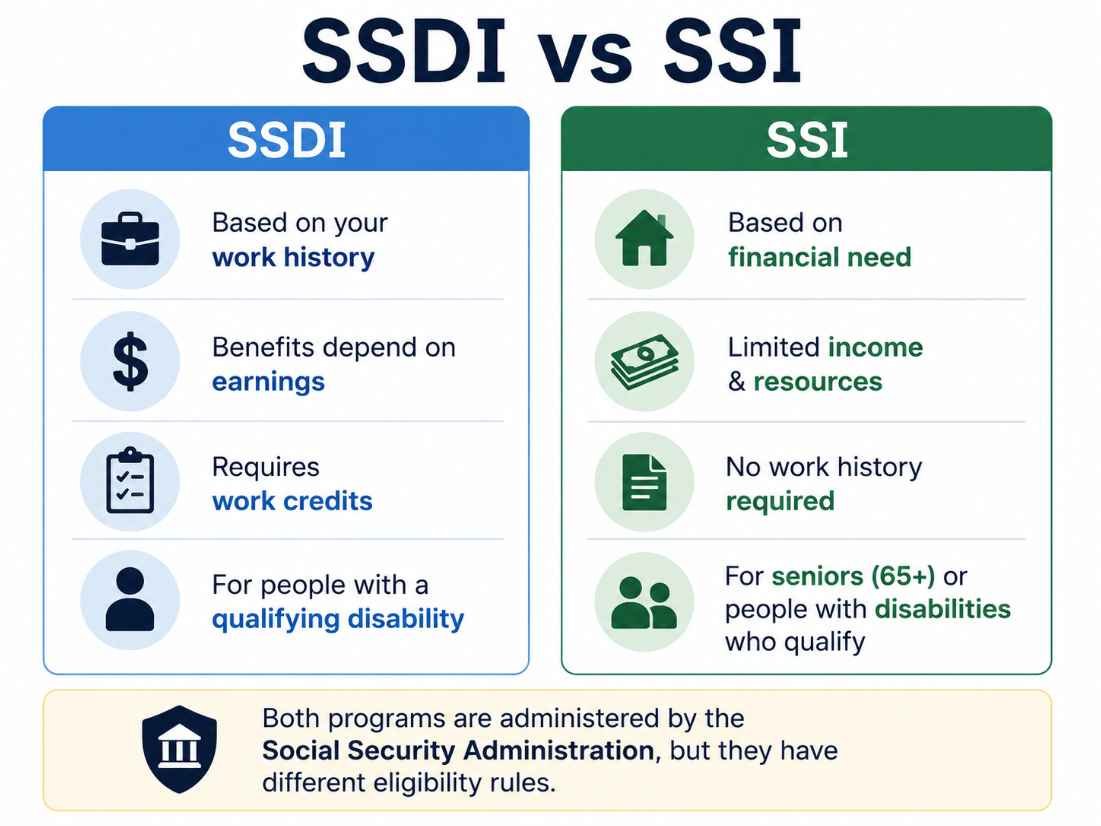
SSDI is insurance you paid into through your work history. SSI is need-based assistance for people with very limited income and resources, regardless of work history. That's it. Everything else follows from that one distinction.
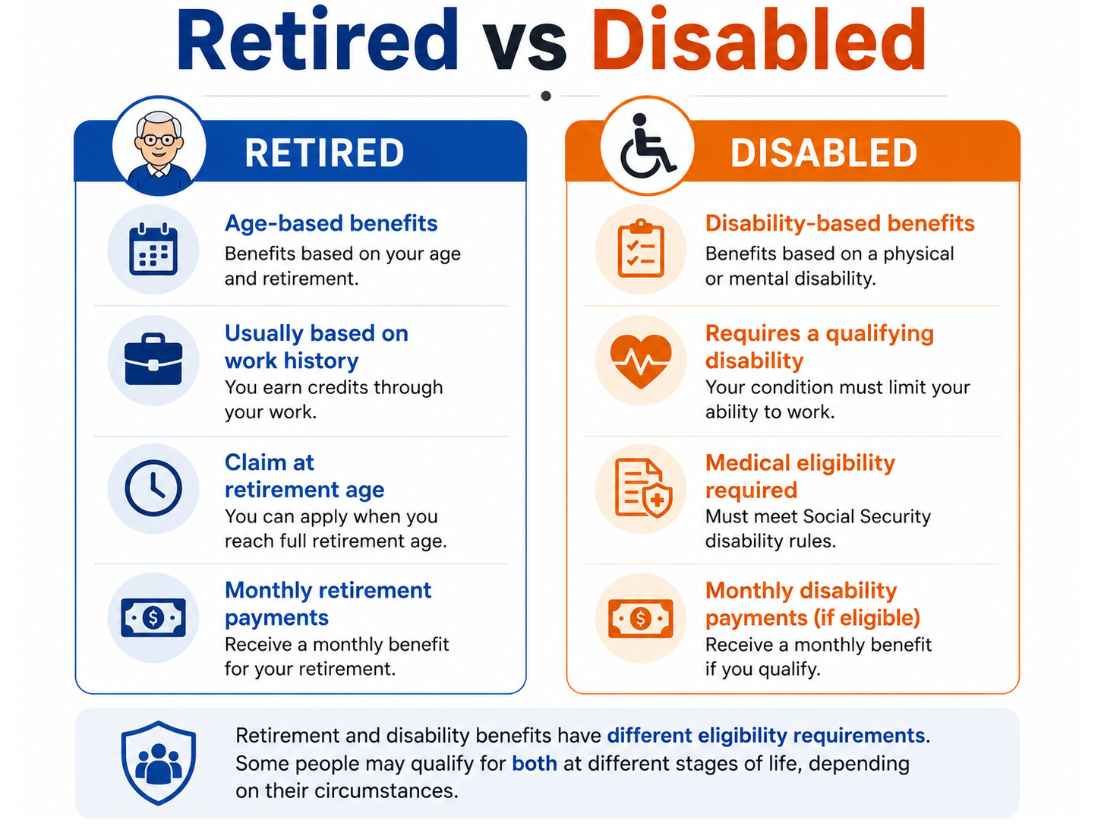
Quick gut check: if you worked and paid Social Security taxes for years before becoming disabled or retiring, you're almost certainly dealing with SSDI. If you have little to no work history and very limited savings, you're likely looking at SSI.
SSDI vs SSI, side by side
| SSDI | SSI | |
|---|---|---|
| Funded by | Your Social Security payroll taxes | General federal tax revenue |
| Based on | Your work history and earnings record | Financial need, regardless of work history |
| Asset limit | None | Around $2,000 for an individual |
| 2026 max monthly payment | Varies by earnings record, can exceed $2,000+ | Federal max around $994 |
| Health coverage | Medicare, after a waiting period | Usually Medicaid, often immediate |
| Other income effect | Doesn't reduce your check directly, but can affect eligibility if you're working | Can reduce your payment dollar for dollar in some cases |
visual comparison chart
Why other income treats them so differently
Here's the question that actually started this article: does a pension or annuity count against you? On SSDI, generally no. It's an earned-benefit program tied to your work record, not your current bank balance, so a pension usually doesn't reduce your SSDI check.
On SSI, it's a different story. Since SSI exists specifically for people with very limited income and resources, other income, including a pension or annuity, can reduce your SSI payment, sometimes close to dollar for dollar after a small exclusion. This is precisely why one commenter asking about an $878 monthly annuity needs a very different answer depending on which program applies to her.
Already sorted out your pension situation? We covered exactly how pension income gets treated in our companion article.
Read: Is Pension Considered Income →A real mix-up worth avoiding
If you assume SSI rules apply to your SSDI check, you might turn down part-time work or a small pension out of fear it'll wipe out your benefit, when it wouldn't have. Or the reverse: assume SSDI's looser rules apply to SSI and get an unpleasant surprise at your next review. Confirm which program you're actually on before making decisions based on either set of rules.
income sources flowing into a benefits decision
Can you work while on SSDI or SSI?
Yes, on both, but the limits differ. SSDI has a "Trial Work Period" letting you test working without immediately losing benefits, followed by a substantial gainful activity threshold that determines ongoing eligibility. SSI has its own earned income exclusion, then reduces your payment gradually as earnings rise, rather than cutting you off sharply.
Neither program's earning rules are simple enough to eyeball. If work is on the table, a call to the SSA or a local benefits counselor before you start is worth more than guessing.
What this means for your rent budget
Whichever program applies to you, the budgeting step is the same: use your actual, current monthly payment, not an average or a max figure you saw online. SSI's $994 federal maximum, for example, isn't what everyone gets. State supplements and individual circumstances push real numbers up or down.
Once you know your real number, from SSDI, SSI, a pension, or all of the above, the next step is the same 30-second math we keep coming back to: total monthly income minus rent and essentials.
person checking their number on the calculator]
Add your SSDI, SSI, or combined income and see your real gap.
Can I Afford My Rent? →Common questions
Can you get SSDI and SSI at the same time?
Yes, this is called "concurrent benefits." It usually happens when your SSDI payment is low enough that you still qualify for a partial SSI payment on top of it. The SSA determines this automatically when you apply.
Does SSDI check your bank account or assets?
No. SSDI has no asset or resource limit since it's based on your work record, not your financial need. SSI does have a resource limit, generally around $2,000 for an individual.
Which one pays more, SSDI or SSI?
It depends entirely on your work history. SSDI payments are calculated from your past earnings and can be significantly higher than SSI's federal maximum. Someone with a strong earnings record before becoming disabled will usually receive more through SSDI than the SSI federal cap.
Do I need to apply separately for SSDI and SSI?
You typically file one application, and the SSA determines which program, or both, you qualify for based on your work history and financial situation.